CFTC Warns Prediction Markets Over "Mention Contracts" and Manipulation Risks
The CFTC's Division of Market Oversight says "Mention Market" event contracts -- tied to whether someone says certain words, attends an event, or interacts with another person -- may be presumptively susceptible to manipulation.

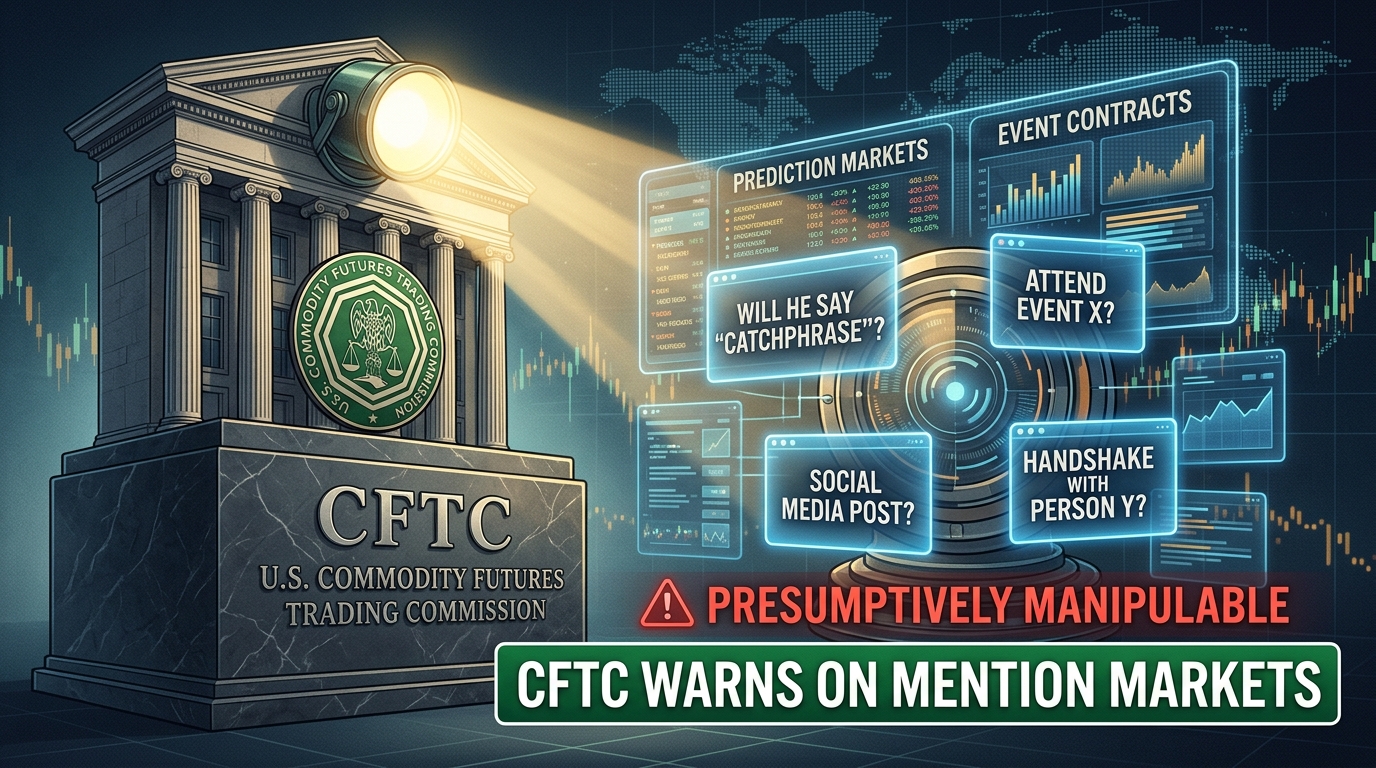
The U.S. Commodity Futures Trading Commission's Division of Market Oversight (DMO) issued a staff advisory on September 22, 2026 warning that a category of event contracts it calls "Mention Markets" — contracts that settle on whether a specific person says certain words, attends an event, or interacts with another person — may be presumptively susceptible to manipulation. The advisory, CFTC Letter No. 26-27, sets out what exchanges are expected to show before listing such contracts. It is staff guidance, not a new rule, and it does not ban Mention Markets or delist any contract currently trading.
What "Mention Markets" Are

The CFTC's own letter defines the category directly: event contracts "based on whether an individual will say or 'mention' certain words, attend or appear at an event, or otherwise interact with another person." The letter uses a podcast host uttering a catchphrase as an illustrative example, and also describes contracts tied to a person's words during a speech, an earnings call or a social-media post, as well as contracts tied to attendance or interactions such as a handshake or a photograph together. "Mention Markets" is the term the CFTC itself adopted for this advisory, building on language already used informally in the industry and press.
Why the CFTC Considers These Contracts Different
Most event contracts already trading on CFTC-registered exchanges settle on outcomes nobody controls alone — an economic data release, an election result, the outcome of a regulated sporting event. Mention Markets are different, the letter says, because their settlement "turns ... on the discrete conduct of a named person," conduct that "may be neither independently generated nor externally verifiable." The advisory states that Division staff "may view Mention Markets as presumptively readily susceptible to manipulation and accordingly expect a heightened showing" before a Part 40 filing to list one would be approved. A footnote clarifies this isn't limited to a single individual: a small group acting together could raise the same concern.
The Manipulation Risks the CFTC Identified
The letter lays out several interrelated concerns. Because the outcome is often within a small number of people's control, it can be comparatively easy for the person involved — or someone close to them — to cause, prevent or influence the result for personal gain. Those closest to the outcome, the letter notes, "frequently possess advance knowledge — such as access to scripts, prepared remarks, guest lists, or unpublished content," which the CFTC treats as material nonpublic information. The advisory also flags that outcomes can be manipulated indirectly, "through that individual — by social engineering, inducement, or public pressure campaigns." Finally, contracts settling on conduct in informal or private settings, or involving people not otherwise subject to public scrutiny, are harder to verify and easier to manipulate without detection.
What Exchanges Are Expected to Consider
Rather than prohibiting the category outright, the advisory sets out four non-exhaustive factors DMO staff will look for in any Part 40 filing for a Mention Market contract: whether the person controlling the outcome is bound by independent legal, professional or confidentiality obligations that discourage manipulation; whether the contract is vulnerable to outside pressure directed at that person; whether the underlying conduct is independently verifiable and subject to genuine public scrutiny; and whether the exchange has built robust trading rules, surveillance and controls — such as restricted-participant lists or position limits — to detect and deter manipulation. The letter states that in "limited circumstances," a well-designed contract paired with strong exchange controls can rebut the presumption and support listing the contract consistent with existing rules.
What This Advisory Is — and Is Not
The letter is unambiguous about its own legal status. It states plainly that it "is informational and does not create new obligations, nor supersede the Act or Commission regulations thereunder," and its conclusion goes further: the advisory "is not intended to, does not, and may not be relied upon to create any rights, substantive or procedural, enforceable by law by any party," does not amount to a no-action position, and "is not intended to, does not, and may not be relied upon to create any new binding rules or regulations." It represents the views of DMO staff, not necessarily the Commission as a whole. It is not an enforcement action, and it does not automatically delist any Mention Market contract already trading. The obligation the letter describes — that exchanges list only contracts "not readily susceptible to manipulation" — already exists under DCM Core Principle 3; the advisory explains how DMO staff will apply that existing standard to this specific contract category going forward.
No specific exchange, operator or contract is named anywhere in the letter's text. The advisory is addressed to designated contract markets generally — the CFTC-registered exchanges, such as Kalshi, that list event contracts for U.S. traders — rather than to any single company.
The Wider Prediction-Market Backdrop
The advisory does not exist in isolation. It references a broader rulemaking process the CFTC opened in June 2026 — a Federal Register notice on "Prediction Markets; Public Interest Determinations" proposing amendments to Part 40 — which separately discussed how sports contracts tied to a single player's actions can raise comparable manipulation concerns. The September 22 letter is a narrower staff advisory under existing authority, not part of that rulemaking itself. Separately, trade press has connected the advisory to earlier CFTC enforcement matters involving improper trading on mention-style contracts, including a case involving a former White House staffer accused of trading on advance access to presidential remarks; those cases are distinct enforcement matters and are not addressed in this advisory.
Bottom Line
As of September 27, 2026, the CFTC has not banned Mention Market contracts, has not taken enforcement action tied to this advisory, and has not named any operator as being in violation of anything. What it has done is put designated contract markets on notice that this category of contract will face a higher bar when it comes to demonstrating compliance with the existing rule against contracts that are readily susceptible to manipulation, and it has told them, in some detail, what that showing should look like.
Reporting & Methodology
This article is based on the full text of CFTC Letter No. 26-27 and the accompanying CFTC Press Release 9302-26, both fetched directly from cftc.gov, cross-checked against legal and trade-press analysis (Reed Smith, The Block, Investing.com, CryptoTimes) for context and framing. No claim in this article states or implies that any specific operator has been found in violation of anything, consistent with the advisory's own text, which names no company.
More from Regulation
- Brazil: Lula Re-Elected as Congress Considers Fixed-Odds Betting Ban
- UK Budget Preview: Gambling Duties and the Machine Games Duty Debate Before 28 October
- Ohio Orders 10 Prediction-Market Platforms to Stop Offering Sports Contracts
- AGCO Fines theScore.Bet C$200,000 Over Cash-Out Offers It Did Not Honour